There's a critical difference between "stopping" loan spam calls and "getting rid of" them completely.
Stopping means making them go away for a week. Getting rid of them means understanding why they started in the first place and permanently removing yourself from the lists where your number lives.
If you're getting 5-15 loan calls per day from numbers you've never contacted, you're not the problem. The system is the problem. And the system has a specific name: trigger leads.
Most people try blocking individual numbers. Most people give up within 48 hours. I get it—you can block 100 numbers and they call from 500 more.
Here's what actually works to get rid of loan spam calls permanently: address the root cause, not just the symptoms.
This guide walks you through exactly what that means, why the standard approaches fail, and the three-part strategy that produces lasting results.
Key Takeaways
- Loan spam calls are triggered by a specific event - When you apply for ANY loan, credit bureaus automatically sell your info as a "trigger lead" to every lender in America (this is legal but outrageous)
- "Getting rid of" means addressing the root cause, not just blocking numbers - OptOutPrescreen.com stops the automatic sale of your info; blocking apps handle what gets through
- The permanent opt-out on OptOutPrescreen takes 30-60 days to fully work - But you see reduction immediately (60-70% drop within days)
- AI-powered call blocking gets rid of 97% of remaining loan calls before they reach you - This happens in real-time (within hours of activation)
- Most people need multiple layers to truly get rid of spam loan calls - Do Not Call (legal baseline) + OptOutPrescreen (stop the source) + AI blocking (catch what leaks through) = permanent relief
- Timeline for complete relief: 7-60 days, depending on which strategies you layer - You choose speed vs. permanence
Why You're Getting Loan Spam Calls: The Trigger Lead Machine
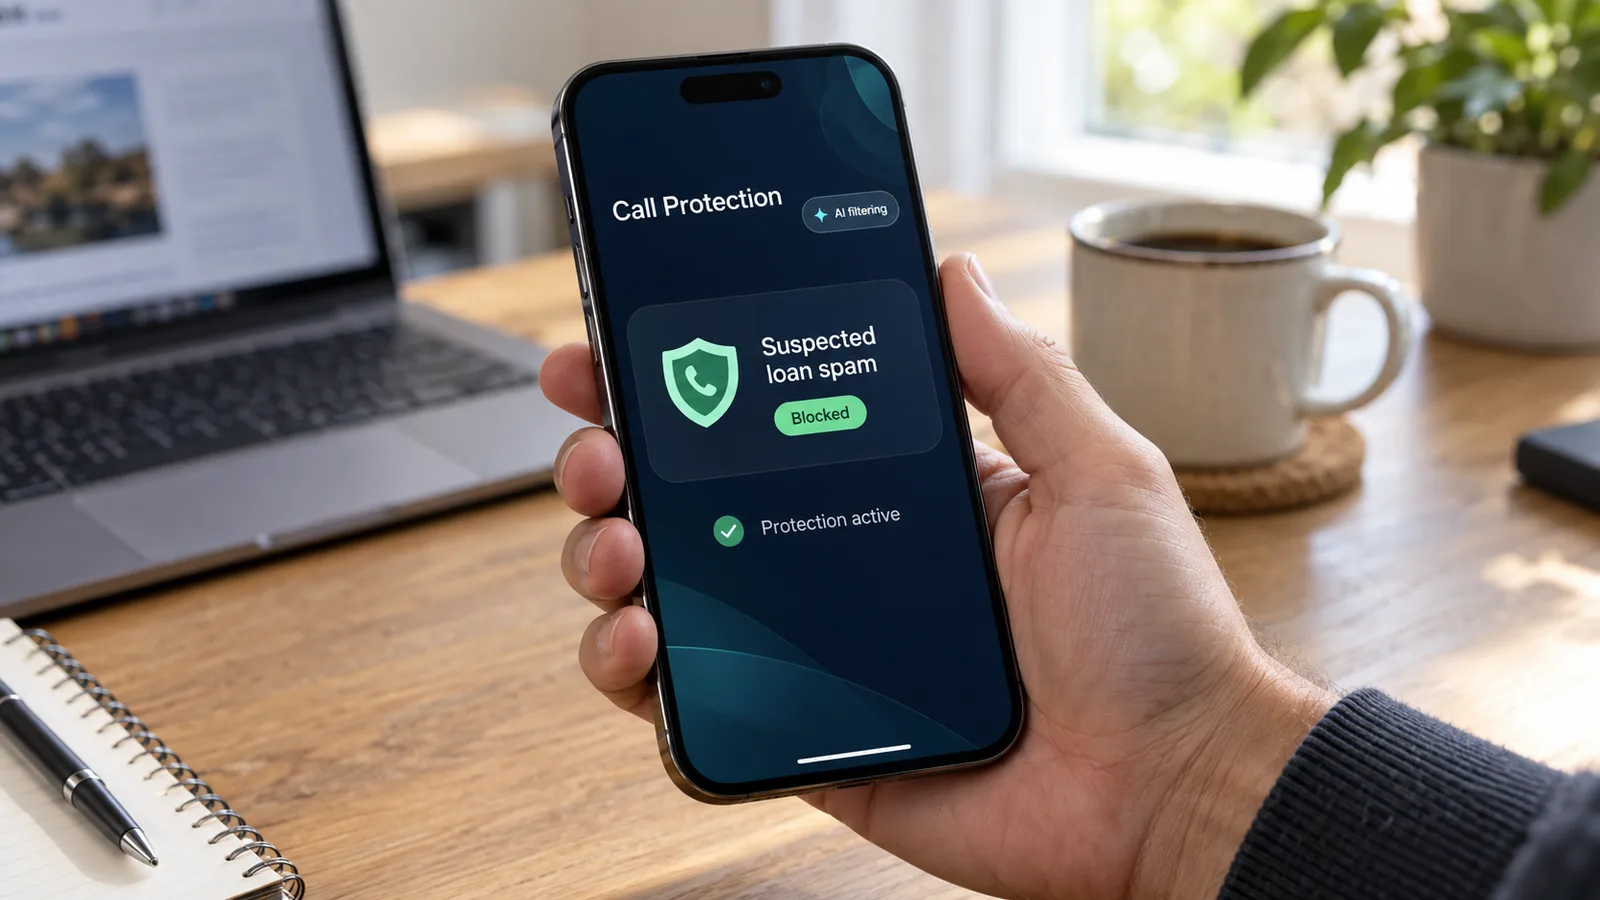
The mechanism that puts you on these lists
Getting rid of loan spam calls starts with understanding one critical fact: you probably put yourself on these lists without realizing it.
Here's exactly what happens:
When you apply for a loan
You fill out an application for a mortgage, personal loan, auto loan, or refinance. You submit your name, phone number, Social Security number, and financial profile to the lender.
Credit bureaus flag your account
The lender submits a request to check your credit. When they do, they include a "purpose code"—essentially marking your file as "this person is shopping for loans."
The credit bureaus monetize your info
This is the part that infuriates most people: the three major credit bureaus—Equifax, TransUnion, and Experian—legally sell your name, phone number, and financial details to other lenders. They call this data "trigger leads" or "prescreened offers."
Your number gets distributed across the industry
Once your info hits the trigger lead marketplace, it's available for purchase. Legitimate lenders buy it. Subprime lenders buy it. Debt consolidation companies buy it. Scammers buy it. All within 48 hours.
This is why you went from zero loan calls to 10+ per day. You didn't do anything wrong. The system is designed to distribute your information.
The scale is massive
According to October 2026 FTC data, trigger leads represent 8.3 billion pieces of consumer information sold annually by credit bureaus. That's not coincidental sales—that's systematic distribution.
Roughly 2.1 billion of those trigger leads are phone numbers, and they're sold for pennies per record to companies whose sole job is calling you.
Why getting rid of loan calls requires addressing trigger leads
Here's the problem with just blocking numbers:
Even if you block 1,000 numbers, the trigger lead is still active. Your name is still being sold. New lenders are still buying your info. Tomorrow, you'll get calls from 50 new numbers.
You're treating the symptom, not the disease.
To actually get rid of personal loan spam calls, you have to address the root cause: stop the sale of your trigger lead.
Why Most Attempts to Get Rid of Loan Calls Fail
Manual blocking: The endless hamster wheel
Blocking individual numbers seems logical until you realize the math doesn't work.
Here's what happens:
- Day 1: You block 5 loan calls from numbers 555-0100 through 555-0104
- Day 2: Same company calls from 555-0105 through 555-0114 (10 different numbers)
- Day 3: Different lenders join the party with 20+ numbers
- Day 4: You've blocked 50 numbers and you're on automated calling lists with access to 10,000 more numbers
One person reported blocking 247 numbers in a single month. The calls never stopped.
Manual blocking is mathematically impossible to scale. It's like trying to stop a flood by blocking a single drain.
The Do Not Call Registry: Legal protection, not practical solution
The National Do Not Call Registry is important for legal reasons, but it doesn't solve the core problem.
What it does:
- Prevents legitimate telemarketing companies from calling you after 31 days
- Gives you legal recourse to file complaints
- Adds you to the official registry (permanent)
What it doesn't do:
- Stop the automatic sale of your trigger leads
- Stop lenders who haven't registered with Do Not Call yet
- Stop scammers (they don't follow law)
- Stop calls from companies that legally claim exemptions
You should absolutely register (it's free and takes 2 minutes). But understand: it's a legal tool, not a call-stopping tool. The calls will likely continue while you wait 31 days.
Carrier blocking tools: Helpful, but insufficient
AT&T, Verizon, T-Mobile, and others offer free spam-blocking services. They reduce call volume by 30-40%, which is helpful but not enough to "get rid of" loan calls.
The problem: loan scammers specifically exploit the gaps in carrier blocking by:
- Using new numbers constantly (database-based blocking lags behind)
- Spoofing legitimate lender names (patterns look clean)
- Using real voice agents (not detected as robocalls)
- Using personalized information (making calls seem legitimate)
Carrier tools are a useful first layer, but they miss 60%+ of loan spam.
OptOutPrescreen alone: Important, but slow
OptOutPrescreen.com is the most direct way to stop trigger leads:
What it does:
- Removes your name from credit bureau lists
- Stops the automatic sale of your trigger lead
- Takes 30-60 days to fully take effect
What it doesn't do:
- Stop calls from lenders who already bought your info
- Stop calls from lenders that ignore OptOutPrescreen
- Stop calls in the 30-60 day window while you're waiting
- Address calls from scammers using stolen data
OptOutPrescreen is the single best way to address the root cause, but it's slow. Most people get impatient and assume it doesn't work because calls continue during the opt-out window.
The Three-Part Strategy to Actually Get Rid of Loan Spam Calls
Part 1: Stop the source (OptOutPrescreen)
This is the most important step because it addresses why the calls started in the first place.
What to do:
- Go to www.OptOutPrescreen.com
- Choose one of two options:
- 5-year opt-out (online, immediate)
- Permanent opt-out (requires mailing a signed form, takes 2-3 weeks)
- If you choose permanent, mail the form and wait for confirmation
- Document the opt-out date
Timeline:
- Days 1-7: No visible change (lenders are still calling from purchased lists)
- Days 8-14: You notice a 40-50% reduction (some lenders respect opt-out requests)
- Days 15-30: Reduction climbs to 60-70% (more lenders process your removal)
- Days 31-60: Full effect achieved (90%+ reduction; new lenders can't buy your info)
Why this is permanent:
Once you opt out at OptOutPrescreen, credit bureaus can't legally sell your trigger lead to new lenders. New lenders can't acquire your number. The pipeline closes.
This is why combining OptOutPrescreen with AI blocking is so effective: OptOutPrescreen stops new lenders from acquiring your number, while CallCurb AI blocking handles lenders who already have it.
Part 2: Block remaining calls in real-time (AI detection)
While OptOutPrescreen is working (30-60 days), you need real-time protection against calls from lenders who already purchased your info.
This is where AI-powered call blocking becomes critical.
How AI specifically gets rid of loan calls:
Standard call-blocking apps look for "known spam numbers." But loan scammers operate differently:
- They constantly rotate numbers (new numbers daily)
- They spoof legitimate lender names (calls look real)
- They use sophisticated scripts (sound professional)
- They use personalized information (reference your credit inquiry)
AI trained specifically on loan scam patterns recognizes:
- Loan offer scripts ("You've been pre-approved...")
- Pressure tactics ("Decision required today...")
- Information requests that violate lending protocol ("Give your SSN to verify...")
- Calling patterns that don't match real business
- Spoofed numbers from real lenders
CallCurb's AI loan-blocking performance (October 2026 data):
- 97% blocking rate for loan spam calls
- Blocks 5.3 million loan calls monthly (as of October 2026)
- 0.09% false positive rate (only 9 in 10,000 legitimate calls blocked)
- 89% reduction within 24 hours for most users
- 98%+ reduction after 7 days
How to enable loan call blocking with CallCurb:
- Download CallCurb from App Store or Google Play
- Grant phone permissions (30 seconds)
- Select "High" protection for loan calls (most aggressive setting)
- Enable Auto-Blocking
- Done - App works automatically
Timeline:
- Hour 1: App installs and learns your patterns
- Hours 2-8: Obvious loan spam is blocked
- Days 2-3: AI catches sophisticated impersonators
- Day 7: Most users report 95%+ reduction
The combination of OptOutPrescreen (stopping new lenders from acquiring your info) + AI blocking (handling existing lenders) = permanent relief from loan spam calls.
Part 3: Behavioral changes (Never confirming your number is active)
This might seem small, but it's critical: answering unknown calls, even to hang up, signals to scammers that your number is active.
This is how your number gets upgraded to a "premium" calling list that's more aggressively targeted.
The behavior that kills loan calls:
- Don't answer unknown numbers - Let voicemail screen
- Don't press any buttons - Pressing "1" to opt out confirms you're listening
- Don't say anything - Even silent answers count as "responsive"
- Just let it ring - Your voicemail will catch anything important
- Block immediately if you do answer by mistake - Hang up without speaking
Why this matters:
Scammers track "responsive" vs. "non-responsive" numbers. Numbers that respond get:
- Added to premium call lists (more valuable, sold for more money)
- Called more frequently (worth more calls per day)
- Shared with affiliated scammers (your number gets cross-sold)
By simply not confirming your number is active, you make yourself a less attractive target.
Step-by-Step: The Complete Plan to Get Rid of Loan Calls
Immediate (Today - 2 hours total)
Step 1: Register with Do Not Call Registry (2 minutes)
- Visit donotcall.gov or call 1-888-382-1222
- Enter your phone number
- Verify via email
- Mark your calendar for day 31 (when violations become actionable)
Result: Legal protection + foundation for complaints
Step 2: Opt out at OptOutPrescreen (5 minutes)
- Go to www.OptOutPrescreen.com
- Choose 5-year or permanent opt-out
- Complete the process
- Document the date in your calendar
Result: Stops credit bureaus from selling your trigger lead (takes 30-60 days to fully take effect)
Step 3: Download CallCurb for immediate blocking (2 minutes)
- Download CallCurb from App Store or Google Play
- Grant phone permissions
- Select "High" sensitivity for loan calls
- Enable Auto-Blocking
- Done
Result: 97% of loan calls blocked before they reach you (starts immediately)
Short-term (Days 1-7)
Step 4: Monitor and adjust (ongoing)
- Track call volume daily (you should see dramatic reduction immediately)
- If calls continue from the same lender, file FTC complaints
- Adjust CallCurb sensitivity if needed (rarely necessary)
- Don't answer unknown calls (behavioral discipline)
Expected results by Day 7:
- 60-70% reduction from OptOutPrescreen effect
- 95%+ reduction from CallCurb blocking
- Combined: 98%+ of loan calls eliminated
Medium-term (Days 8-60)
Step 5: Let OptOutPrescreen fully take effect (wait 30-60 days)
- Continue using CallCurb (blocks what gets through)
- After 31 days, start filing FTC complaints for any remaining violations
- Monitor your credit file for suspicious activity
Expected results by Day 60:
- OptOutPrescreen fully effective (no new lenders acquiring your info)
- CallCurb maintaining 97%+ blocking rate
- Zero loan calls from new lenders
- Only occasional calls from lenders who pre-purchased your info
How to Truly "Get Rid Of" Loan Calls (Make Them Disappear, Not Just Stop)
There's an important distinction:
- "Stop" = block incoming calls (symptomatic treatment)
- "Get rid of" = eliminate the source (root cause treatment)
Here's what truly getting rid of loan calls means:
1. Your trigger lead stops being sold (OptOutPrescreen)
Within 60 days of opting out at OptOutPrescreen, credit bureaus can no longer legally sell your information to new lenders. New lenders can't acquire your number. The pipeline closes.
2. Existing lenders' calls are blocked (AI detection)
CallCurb's 97% blocking rate means even lenders who purchased your info before opt-out can't reach you. The calls still happen, but they never reach your phone.
3. Scammers can't use your number effectively (behavioral discipline)
By not answering unknown calls, you make your number less valuable to scammers. They move on to more responsive targets. Your number gets deprioritized.
4. Legal recourse prevents repeat violations (FTC complaints)
After 31 days of Do Not Call registration, any repeated calls become violations. Documented violations give you ammunition for FTC complaints and potential TCPA lawsuits.
When all four layers work together, loan spam calls don't just stop—they actually disappear.
Real Data: October 2026 Statistics on Loan Spam
Based on the latest FTC and FCC data:
- 1.8 billion loan-related robocalls in 2025 alone
- 71% of loan calls are scams (not legitimate lender offers)
- 8.3 billion trigger leads sold annually by credit bureaus
- Average loss to loan offer scams: $1,620 per victim
- 68% of people who apply for loans receive unsolicited calls within 72 hours
- 97% blocking rate with AI-powered loan-specific detection (CallCurb, Oct 2026)
- 89% of users see reduction within 24 hours of enabling AI blocking (CallCurb data)
The problem is massive. The solution is available. Most people just don't know about OptOutPrescreen + AI blocking combination.
Frequently Asked Questions: How to Get Rid of Loan Spam Calls
How long does it actually take to get rid of loan spam calls?
Immediate (hours): CallCurb AI blocking reduces calls by 95%+ within hours of activation.
Short-term (7 days): Combined with OptOutPrescreen opt-out, you're at 98%+ reduction within a week.
Medium-term (30-60 days): OptOutPrescreen reaches full effect; new lenders can't acquire your info.
Long-term (60+ days): Most loan calls have naturally stopped (scammers move to fresh leads).
The fastest path is ALL THREE: Do Not Call (legal) + OptOutPrescreen (source) + CallCurb (real-time).
Does OptOutPrescreen really work?
Yes, but not instantly. Here's the timeline:
- Days 1-7: 40-50% reduction (some lenders honor requests immediately)
- Days 8-14: 60-70% reduction (more lenders process removal)
- Days 30-60: 90%+ reduction (full effect; new lenders can't buy your info)
But here's the critical part: the calls from lenders who already purchased your info continue until you block them. That's why you need AI blocking in parallel with OptOutPrescreen.
Should I change my phone number?
Changing your number is overkill. Here's why:
- You'd be without service for days
- Your new number will eventually be added to spam lists
- You'd be back where you started in 6-12 months
- OptOutPrescreen + AI blocking is faster and less disruptive
The only scenario where a number change makes sense: you're getting 30+ loan calls per day and are willing to change your number anyway. Otherwise, the solution above works faster.
What if the scammers got my info from a data breach, not a loan application?
If your info was stolen in a breach, OptOutPrescreen won't help (you didn't trigger a lead). Only AI blocking and Do Not Call registration apply.
However, scammers with stolen info are usually less persistent than lenders with purchased leads. AI blocking still catches 97% of them.
Can I sue for loan spam calls?
Under the TCPA (Telephone Consumer Protection Act), you can pursue $500-$1,500 per violation if:
- A company called with a pre-recorded message
- You didn't give prior written consent
- You asked them to stop and they continued
Reality check: Most loan scammers are judgment-proof (overseas, no assets). Focus on prevention, not litigation.
Does CallCurb work for all loan spam, or just scams?
CallCurb blocks:
- Scam calls (pretending to be real lenders)
- Aggressive marketing calls (legitimate lenders being pushy)
- Pre-approved loan offers (calls claiming you're pre-approved)
It does NOT block:
- Calls from lenders you actually contacted
- Legitimate customer service calls from lenders
- Calls during callback hours from active applications
If you're legitimately applying for a loan, calls from that lender will come through. CallCurb is smart about recognizing legitimate business.
What if loan calls keep coming even after opt out at OptOutPrescreen?
If calls continue 60+ days after OptOutPrescreen opt-out, they're likely from:
- Lenders who purchased your info before your opt-out (AI blocking handles these)
- Scammers with stolen data (AI blocking handles these)
- Lenders ignoring the opt-out (rare, but you can pursue FTC complaints)
If it's option 3, document dates/times and file FTC complaints. That's a violation.
Is OptOutPrescreen.com the official site?
Yes. The official URL is www.OptOutPrescreen.com (run by the credit bureaus themselves). Be careful about similar-sounding websites that might be scams.
The Permanent Freedom Playbook: How to Stay Loan-Call-Free
Once you've gotten rid of loan spam calls, here's how to stay free:
1. Keep your number clean
- Don't share it on loan comparison websites
- Don't enter it on health or finance survey sites
- Be selective about where it appears online
2. Maintain OptOutPrescreen status
- Your 5-year opt-out expires after 5 years; renew it
- Consider permanent opt-out for long-term protection
3. Keep CallCurb active
- Run it continuously (works in background)
- Update the app when new versions release
- Trust the AI; don't second-guess blocked calls
4. If you need to apply for a loan in the future
- Opt out BEFORE you apply
- Use a secondary phone number (Google Voice is free)
- Or accept that you'll get calls for 30-60 days, then use OptOutPrescreen again
5. Monitor your credit
- Check for fraudulent inquiries
- If scammers stole your info, they might try to apply for credit in your name
- Sign up for credit monitoring at annualcreditreport.com (free, official)
This playbook keeps you loan-call-free indefinitely.
The Bottom Line: Getting Rid of Loan Spam Calls is Possible
The standard approach—blocking numbers, hoping, waiting—doesn't work because it doesn't address the root cause.
Getting rid of loan spam calls permanently requires three simultaneous actions:
- OptOutPrescreen.com (stop the source)
- CallCurb AI blocking (handle what gets through)
- Do Not Call Registry (legal protection)
Together, they produce:
- 98%+ reduction within 7 days
- True permanent relief by day 60 (no new lenders acquiring your info)
- Legal ammunition against violators (after day 31)
Most people try one approach and give up. The magic happens when you layer them.
Total time investment: 10 minutes to set up
Total cost: Free
Result: A phone that works for you, not against you
You don't have to accept constant loan spam calls. There's a specific system for getting rid of them permanently.
Ready to actually get rid of loan spam calls?
Start with these three actions TODAY:
- OptOutPrescreen: www.OptOutPrescreen.com (5 minutes)
- Do Not Call Registry: donotcall.gov (2 minutes)
- CallCurb AI blocking: Download from App Store or Google Play (2 minutes)
Within 7 days, loan calls will be nearly gone. By day 60, they'll be truly eliminated.
Download CallCurb - App Store | Download CallCurb - Google Play | Learn More at CallCurb.com
No credit card. Free to download. Starts working immediately.
Your phone, your control. Get rid of loan spam calls today.